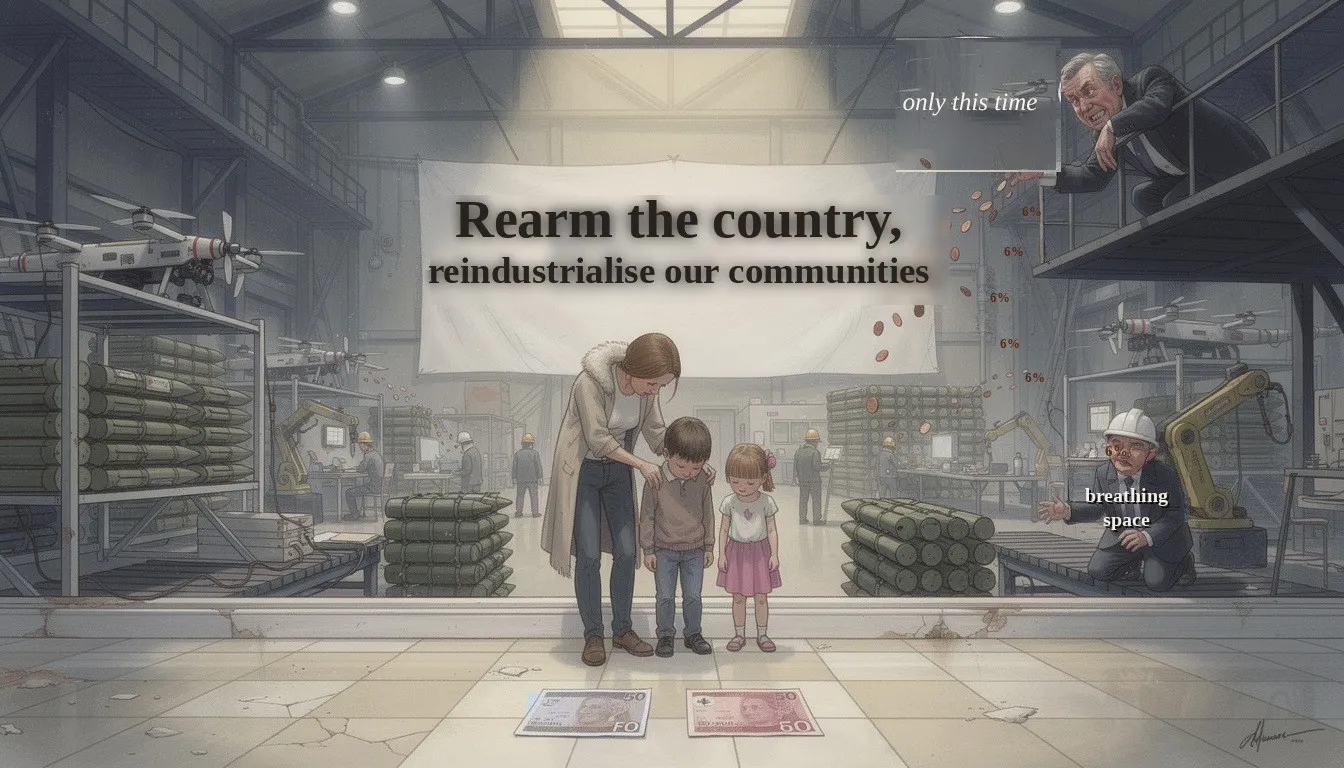
A Winter Coat and a Mortgage, or: What Britain's Budget Bought With Borrowed Time
The Budget hands out £5bn of relief in this financial year and the next, and funds it with tax rises that do not start until April 2027 and a defence commitment that never stops rising. One is a winter coat. The other is a mortgage.
A hundred pounds will arrive this winter. It will arrive in the same financial year as the VAT holiday on electricity and the freeze on fuel duty, and all three of them are paid for, in the first instance, with borrowed money. The revenue that is meant to replace that borrowing does not arrive this winter. It arrives in April 2027, when the tax on savings interest rises by another two percentage points and the full new state pension crosses above the frozen personal allowance, and it keeps arriving after that — in April 2028, in April 2029 — as the capital allowances change and the fiscal drag tightens on people who were told this was help.
Read the two clocks together and the Budget’s method appears. The money goes out now. The money comes back later. The relief is front-loaded by design and the restraint is back-loaded by design, and in the years between — while the relief is still being felt but the revenue has not yet landed — sits a commitment that does not expire at all: £298bn of Ministry of Defence spending over four years, a £15bn uplift above the settlement the government itself agreed in 2025, rising on its own published plans toward 3% of GDP by 2030 and 3.5% by 2035.
This is the point here. The Budget is not, in its structural content, a cost-of-living package. It is a rearmament budget with a cost-of-living package attached — and the package is written to expire before the rearmament bill is fully felt. One is a winter coat. The other is a mortgage. And the document itself shows how the mortgage is paid.
The method
Start with the timing, because the timing is the argument.
The £100 household payment, the electricity VAT relief and the fuel-duty extension all land in this financial year and the next. Together the three cost-of-living measures cost about £5.04bn over four years, and the bulk of it falls in 2026/27 and 2027/28. The revenue meant to offset that spending arrives on an entirely different clock. The additional two percentage points on savings and property income tax do not change until April 2027 and do not yield their full billion until 2028/29. The capital allowance changes ramp over the same period. Only the bank and corporation tax surcharge — temporarily rising from 3% to 6% for fifteen months from January 2027, worth £1.5bn and legislated as non-extendable — is timed to match the relief it funds. It is written to expire with it.
The sequence is deliberate. A Chancellor spending the buffer today, and asking the later columns of his own scorecard to refill it. The fiscal rules permit exactly this. They do not demand a balanced budget in any given year. They target a surplus on day-to-day spending and falling net financial debt relative to GDP in a single year — 2029/30 — and the years before that are allowed to run loose. The Budget uses the permission: on its own scorecard, policy adds about £6bn to borrowing this year and £7bn next, and only begins subtracting from 2029/30. The rules are satisfied by a plan, not by an outcome. And the plan, if it holds, hands the bill to a Parliament that does not yet exist.
The winter coat
Now the relief itself, because it is real and it matters to real people, and the point is not to sneer at it. The point is to see what it is for.
Three measures do the work. A Household Energy Payment of £2.63bn, mainly one-off support to households. An electricity VAT relief worth £1.06bn, a temporary tax reduction including the relief introduced before this Budget. A fuel-duty relief of £1.36bn, a temporary tax cut benefiting households and businesses alike. Together, £5.04bn over four years, concentrated in 2026/27 and 2027/28.
Alongside them sit two housing measures: £1.25bn of additional social and affordable housing funding as scored, and £2.70bn of “Your First Home” equity loans — which is not spending in the ordinary sense but lending, within the window, with government acquiring a repayable financial asset in return.
Now put that beside the defence line. In 2026/27 they look like near-equals. The three cost-of-living measures cost about £4.0bn in that year; the defence increase is about £3.4bn. A winter coat and a heavier winter coat, side by side on the scorecard.
Follow them forward and the resemblance collapses.
The mortgage
Defence is a structural commitment. Household relief is a cushion. The two are easy to confuse in the year they are announced and impossible to confuse once you follow the published profile.
The June Defence Investment Plan established approximately £298bn of total Ministry of Defence spending over 2026/27 to 2029/30, including a £15bn uplift above the 2025 Spending Review settlement — profiled at £3.4bn, £3.7bn, £3.9bn and £4.0bn across the four years. Under the published plans the household relief expires, every line of it, by the end of 2027/28. The defence uplift does not expire. It rises, and on the government’s commitments to NATO it keeps climbing toward 3% of GDP by 2030 and 3.5% by 2035. Over the four-year window the defence increase is about three times the relief.
What the money buys, according to the Budget’s own account:
| Area | What the money buys |
|---|---|
| Ammunition and weapons | An £11bn programme to increase stockpiles and weapons provision, including at least six new factories producing explosives and propellants. |
| Drones and autonomous systems | £5bn for surveillance and attack drones, uncrewed vehicles and vessels, and systems operating alongside conventional aircraft and ships. |
| Combat aircraft | £8.6bn for the next-generation fighter programme with Italy and Japan, plus development of aircraft that can operate without onboard pilots. |
| Nuclear deterrence | Replacement submarines, development of a UK warhead and associated capabilities. (£47bn submarines, £13bn warhead, £63.6bn nuclear enterprise over the period.) |
| Space capabilities | £3.2bn of investment in military space capabilities. |
And separately, outside the defence line but part of the same strategic posture: £500m of additional air-defence support to Ukraine this winter, within 2026/27 military support, and a £7bn economic-support package over three years including up to £5.5bn of World Bank guarantees and funding mobilised through the World Bank.
Here is the arithmetic that should stop you. The cost-of-living measures over four years come to £5.04bn. The defence uplift over the same four years comes to £15bn — three times as much — and of that, £4.7bn was left unfunded in June. The Budget now funds it by trimming every department’s capital budget by 1% for three years and drawing on the Treasury’s capital reserve. The mortgage is being paid out of the capital budgets of the departments that run the country.
| Measure | Amount over four years | Nature of support |
|---|---|---|
| Defence Investment Plan uplift | £15.0bn | Additional spending above the 2025 Spending Review settlement |
| Household Energy Payment | £2.63bn | Mainly one-off household support |
| Electricity VAT relief | £1.06bn | Temporary tax reduction, including the relief introduced before this Budget |
| Fuel-duty relief | £1.36bn | Temporary tax reduction benefiting households and businesses |
| Those three cost-of-living measures combined | £5.04bn | Concentrated in 2026/27 and 2027/28 |
| Additional social and affordable housing funding | £1.25bn | Public expenditure within this four-year window |
| Your First Home equity loans | £2.70bn | Lending within this window; government acquires a repayable financial asset |
One is a winter coat. The other is a mortgage, and the Budget even shows how the mortgage is paid.
Who pays, and when
The relief is real. So is the bill. And they do not land on the same people.
Start with the fiscal drag, which is the quietest line in the document and the one that reaches furthest into the lives of people who were promised protection. The full new state pension rises above the £12,570 personal allowance from April 2027. The allowance is confirmed frozen to April 2031. A new Pension Tax Allowance exempts pensioners with no other income from April 2027 — but only to April 2030, and then it lapses. The exemption is temporary. The drag is not. A pensioner whose only income is the state pension — the person the triple lock exists to protect — is being walked into income tax by the interaction of a rising pension and a frozen threshold, and the shelter provided against that has an expiry date the drag does not.
Then the savings tax. From April 2027, tax on savings interest rises by another two percentage points. This is on top of the additional two percentage points on savings and property income tax already scored elsewhere in the Budget. Together those moves are worth about £1bn when fully in effect in 2028/29. The people who pay are not the people who own assets in any structural sense. They are the people who hold modest savings — the buffer of a few thousand pounds that a household builds against a broken boiler or a broken car — and who now find a little more of the interest skimmed to fill a gap created by a war they did not choose and a defence programme they will never see.
There is no further general rate increase for dividends and capital gains. On the face of it, capital income is spared. But the Business Asset Disposal Relief lifetime limit is halved to £500,000 — which is to say that the one meaningful relief available to someone selling a business they built is cut in half, while the rates on income from simply owning stay where they are. The general rates are untouched. The ladder is being pulled up.
And the bank and corporation tax surcharge, the only measure timed to match the relief it funds, rises from 3% to 6% for fifteen months from January 2027, worth £1.5bn and legislated as non-extendable. Fifteen months, and then it goes. The relief it funds expires. The fiscal drag does not. The savings tax does not. The structural spending does not. What expires is the one levy that reaches the City. What stays is everything that reaches the pensioner.
The bill that arrived uninvited
The Budget did not choose this interest bill. It absorbed it.
The conflict in the Middle East pushed up inflation and gilt yields, and because so much of the national debt is index-linked, the interest bill rose almost at once — by £15.4bn in 2026/27 alone, settling at about £12bn a year thereafter, partly offset by improvements elsewhere of about £4bn. The government chose to absorb that deterioration rather than immediately offset it with taxes or spending cuts. It spent the buffer. The margin against the main fiscal rule fell to £15bn. “This is what a buffer is for,” the document says, and the sentence is a request for trust.
It is worth being clear about what happened, because the language of buffers and margins is designed to make it sound like weather. A war elsewhere in the world moved the price of a specific kind of government debt — the kind whose repayments rise with inflation — and that movement added £15.4bn to what the British state must pay its creditors before it buys a single hospital bed or trains a single soldier. Then, because the decision was made not to meet that cost with taxes or cuts in this financial year, it was met with borrowing — borrowing that the same document schedules repayment for in April 2027 and beyond, on the backs of pensioners and savers.
The sequence is: war raises the interest bill; the interest bill is absorbed; the absorption is funded by borrowing; the borrowing is repaid by fiscal drag and savings taxes timed to arrive after the household relief has expired. That is the machine. It is not broken. It is doing precisely what it was built to do — and the point here is that the people who design it do not experience any of these steps as a cost.
Satisfied by a plan
Now the question the Budget does not want asked: will the later restraint actually happen?
The Office for Budget Responsibility notes, with the dryness of an institution that has seen this before, that the fuel-duty rise has now been deferred five times and the electricity VAT cut has already been extended once. Temporary reliefs have a way of becoming permanent features of the landscape. Each deferral is individually defensible. In aggregate they describe a government that cannot bring itself to withdraw a benefit once the public has organised its budget around it — which means the £5.04bn “temporary” line is less likely to expire on schedule than the scorecard assumes.
Departments may need more money than the plans allow, and the plans were set before inflation rose. Faster collection of self-assessment tax produces a one-off £17bn of cash in 2029/30 — but most of that changes when the tax is paid, not how much is owed, and it flatters exactly the year the fiscal rule targets. The Institute for Fiscal Studies calls the very tight public-service spending plans the consolidation’s Achilles’ heel and names the 2027 Spending Review as the crunch point, where many departments will discover what real-terms cuts mean in practice.
So the plan’s credibility rests on three things happening at once: temporary reliefs expiring on schedule despite a five-time precedent against them; departments absorbing real-terms cuts on plans set before inflation; and a one-off cash timing effect being mistaken for a structural improvement in exactly the year that matters. The rules are satisfied by a plan. Whether the plan is satisfied by reality is a different question, and the document does not answer it.
What the state already buys
To see what is being asked to change, look at what the machine does now.
This is where the money goes today, on the HMRC Annual Tax Summary for 2024/25, PESA 2025 basis — not a Budget 2026 figure, but the shape of the thing the Budget is modifying:
| Spending area | £ billion | Share |
|---|---|---|
| Welfare, excluding state pensions | 246.1 | 21.3% |
| Health | 241.8 | 20.9% |
| State pensions | 137.8 | 11.9% |
| Debt interest | 124.7 | 10.8% |
| Education | 118.7 | 10.3% |
| Defence | 63.6 | 5.5% |
| Public order and safety | 51.4 | 4.4% |
| Transport | 46.4 | 4.0% |
| Business and industry | 40.4 | 3.5% |
| Government administration | 23.0 | 2.0% |
| Housing and utilities | 22.3 | 1.9% |
| Environment | 17.1 | 1.5% |
| Culture, sport and libraries | 14.5 | 1.3% |
| Overseas aid | 7.7 | 0.7% |
| EU settlement payments | 0.7 | 0.1% |
Look at that table. The British state is, in its ordinary working, a machine for paying pensions, hospitals, and interest. Those three lines alone — welfare excluding pensions, health, state pensions, debt interest — account for £750.4bn, or 64.9% of everything. Defence is 5.5%.
Now the margin. The Budget is not proposing to shrink the pension line or the hospital line in any dramatic way. It is proposing to grow defence at the margin — £3.4bn this year, rising to £4.0bn a year by 2029/30 and on toward 3.5% of GDP by 2035 — and to fund that growth, at the margin, by trimming every department’s capital budget by 1% for three years. The margin is where the new machine is being built. And the margin is also where the 2027 Spending Review will discover what real-terms cuts mean in practice, according to the IFS. The same margin is being asked to carry both the rearmament and the restraint. It will not carry both. Something gives, and it will not be the submarines.
The state in that pie chart is being asked to become something else — something that, in addition to paying pensions and hospitals and creditors, manufactures explosives and propellants in at least six new factories, builds uncrewed vessels, and develops aircraft that fly without pilots. Those are not cost-of-living measures. Those are not a winter coat. That is a country being restructured, at the level of its industrial base, toward war — and being restructured quietly, one capital line at a time, in a document the public reads for the £100.
Breathing space
So the real contents of this Budget are not the £100.
They are a set of promises about 2029, made by a Chancellor who absorbed a war-driven interest bill, cushioned households for one winter, and committed the country — durably, expensively, and on a rising profile — to rearming. The relief expires by the end of 2027/28. The fiscal drag and the savings taxes start in April 2027 and continue. The defence uplift never expires. The capital budgets are trimmed. The Spending Review of 2027 will reveal what the margin can and cannot carry. And the OBR’s five-time precedent on fuel duty suggests that at least some of the “temporary” relief will outlive the plan that calls it temporary.
Do not make the mistake of calling this a Budget that failed. That is the deepest trap, and it is the one that keeps you believing a better manager can fix what is not a malfunction. A war moved the interest bill; the interest bill was absorbed; the absorption was borrowed against; the borrowing is being repaid by people with modest savings and frozen thresholds while the structural spending rises on a profile designed to outlast every relief it was sold alongside. The system is not malfunctioning. From the point of view of the people who set its instruction — accumulate, and defend the conditions of accumulation — it is delivering precisely what it was built to deliver. Austerity and militarism are not two policies. They are one discipline applied at two scales: the household budget and the state budget, the winter coat and the mortgage, the pain that arrives before the next election and the pain that arrives after it.
“Breathing space” is the right phrase for what has been bought. It describes exactly what the £5.04bn purchased — relief for households through two winters, funded by borrowing, repaid later by others — and exactly how long it lasts. A winter coat is a real thing and it keeps a real person warm. But it is not a roof, and the mortgage on the roof is now being paid out of the capital budgets of the departments that keep the country running.
The question is not whether Britain can afford the winter coat. The question is who pays for the mortgage, and the document answers it with a precision its authors probably did not intend. Pensioners whose only income is the state pension. Savers whose only asset is a few thousand pounds in an account. Departments whose capital budgets are being trimmed to build factories for explosives. The people who cannot move their savings to Jersey. That is who pays. The correct answer to “who pays?” is never “everyone equally.”